Does Homeowners Insurance Cover Water Damage in South Shore MA?
Jump To:
If you’ve ever woken up to water pooling in your basement or discovered a mysterious wet spot spreading across your ceiling, you’re probably wondering: “Is this going to cost me thousands out of pocket?” The short answer? It depends. Water damage coverage can feel like trying to decode a foreign language, but here’s the thing: understanding your policy before disaster strikes could save you serious headache and cash down the road.
Living here on the South Shore, we see it all. From nor’easters that knock out power to your sump pump, to that sneaky pipe behind your water heater that decides to give up on the coldest night of the year. At RestoreNow, we coordinate emergency response and handle all restoration work for homeowners throughout Hanover and surrounding areas.
What Water Damage Does Homeowners Insurance Actually Cover?
The golden rule for water damage coverage is surprisingly simple: if it’s sudden and accidental, you’re probably covered. If it’s gradual or preventable, you’re probably not.
Here’s what typically gets the green light from your insurance company:
- Burst pipes (especially common here during our brutal December-March freeze cycles)
- Water heater explosions or sudden failures
- Appliance malfunctions like washing machines overflowing or dishwashers going rogue
- Accidental overflow from bathtubs, toilets, or sinks
- Ice dam damage (a winter staple for South Shore homeowners)
- Roof leaks caused by storm damage
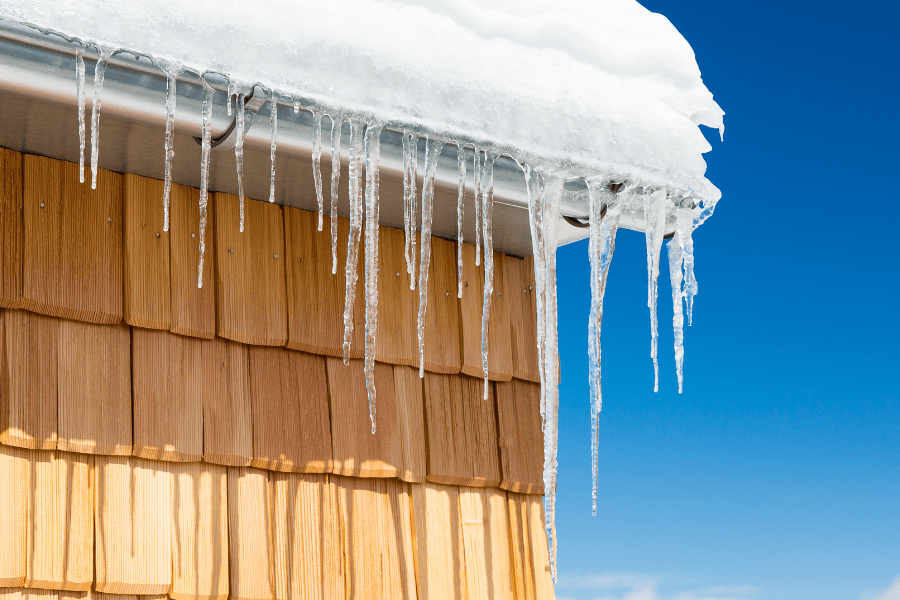
Ice dams are common on South Shore homes during winter months and can cause significant water damage when snow melts and has nowhere to drain.
The key word here is “sudden.” Your insurance company wants to see that you couldn’t have prevented the problem with regular maintenance.
The “Sudden and Accidental” Rule Explained
Think of it this way: if you wake up to a flooded basement because a pipe burst overnight, that’s sudden and accidental. But if you’ve been ignoring a slow drip under your kitchen sink for six months and finally discover major damage, that’s gradual and preventable.
Ready to protect your home?
If you’re dealing with water damage right now, don’t wait.
What Water Damage Is NOT Covered by Standard Policies
Now for the not-so-fun part. Here are the water damage scenarios that’ll likely leave you reaching for your wallet:
Flood Damage from Outside Sources
This is the big one that catches most homeowners off guard. Standard homeowners insurance policies do not cover flood damage, even flooding that occurs in areas away from natural water sources. That includes:
- Heavy rainfall that overwhelms drainage systems
- Hurricane storm surge
- Rapid snowmelt flooding
- Surface water that seeps through foundation cracks
Living on the South Shore, we’re no strangers to hurricanes and heavy storms. According to the National Flood Insurance Program, roughly 20 to 25 percent of flood claims originate from properties outside high-flood-risk areas. So even if you don’t live right on the water, you could still be at risk.
Maintenance-Related Water Damage
Your homeowners insurance will likely not cover water damage that is the result of a faulty sink that has been leaking for several months. Other excluded maintenance issues include:
- Long-ignored roof repairs
- Clogged gutters causing overflow
- Deteriorating pipe joints
- Poor ventilation leading to moisture buildup
Quick Checklist: Is Your Water Damage Covered?
If you answered yes to the first four and no to the last, you’ve got a good shot at coverage.
Special Coverage Options for South Shore Homeowners
The good news? You can beef up your protection with some smart add-ons that make sense for our area.
Sewer Backup and Water Backup Coverage
Adding sewer/water backup coverage to your MA home insurance only costs around $50 per year. For what amounts to a nice dinner out, you get protection against municipal sewer line backups, tree roots blocking underground pipes, sump pump failures, and drain blockages.
Given how many South Shore homes have basements and sump pumps, this is practically a no-brainer.
Flood Insurance Through NFIP
According to the National Flood Insurance Program, just 1 inch of water can cause $25,000 of damage to your home. You can purchase flood coverage at any time, though there is usually a 30-day waiting period before the policy goes into effect.
How RestoreNow Helps Navigate Water Damage Claims
Even when you have coverage, dealing with insurance claims can feel overwhelming. That’s where having the right restoration team makes all the difference.
With our trusted partners, we’ll coordinate emergency water extraction and drying when needed, then RestoreNow handles all the structural restoration work that follows. We make the claims process easier by thoroughly documenting the damage, preparing detailed estimates, and providing the information your insurance company needs to move things forward.
We know what insurers look for, and we make sure the scope of work we propose matches the repairs that are actually needed. That administrative burden? We take it off your shoulders so you can focus on getting your life back to normal.
For immediate assistance with water damage, check out our guide on what to do first after finding water damage in your Hanover home.
Prevention Tips for South Shore Homes
The best insurance claim is the one you never have to file. Here are some South Shore specific tips to keep water where it belongs:
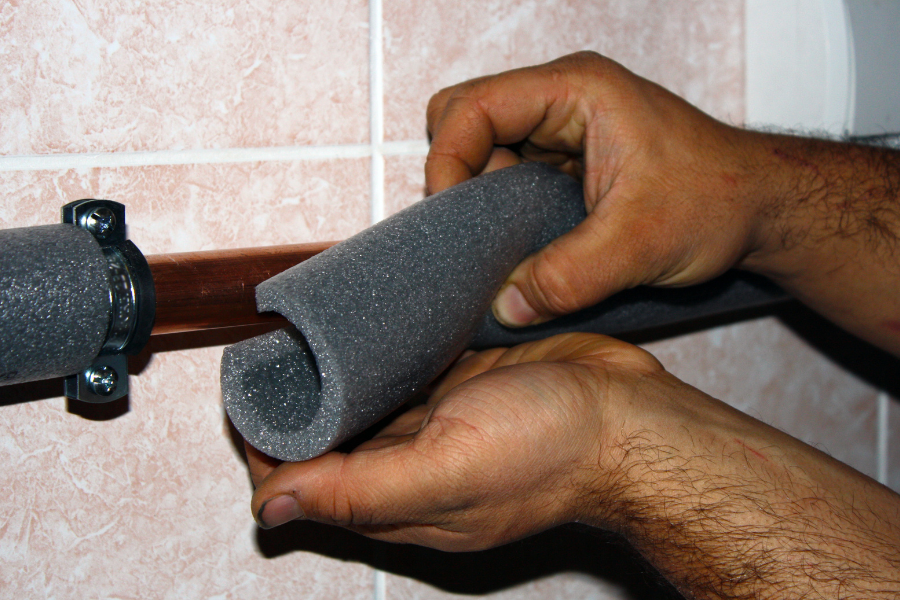
Proper pipe insulation is crucial for South Shore homes during harsh winter months to prevent freezing and bursting.
Winter prep (crucial for our area):
- Insulate pipes in unheated areas
- Keep cabinet doors open during cold snaps to let warm air circulate
- Know where your water shutoff valve is located
Basement maintenance:
- Test your sump pump before spring thaw season
- Install a battery backup system for power outages
- Keep gutters clean and extend downspouts away from your foundation
Want more prevention tips? Read our post about how to detect water damage in your basement before it becomes a major problem.
When to Call Professionals
Small water issues? Maybe you can handle them yourself. But here’s the thing about water damage: it’s sneaky. What looks like a small problem on the surface can hide serious structural issues underneath.
If you’re dealing with more than a few inches of standing water, water that’s been sitting for more than 24 hours, any sewage-related backup, or electrical systems that may have been affected, don’t go it alone.
With our licensed partners, we coordinate emergency mitigation services, then RestoreNow handles the restoration work that gets your home back to its pre-damage condition. For comprehensive restoration services in the South Shore area, visit our service area page to see if we cover your town.
The Bottom Line:
Water damage coverage isn’t as straightforward as we’d like, but understanding the basics can save you thousands. Most sudden, accidental water damage from inside sources gets covered, while floods and maintenance-related issues typically don’t. Smart add-on coverage for sewer backup and flood protection can fill the gaps for around $50-100 extra per year.
When disaster does strike, having a restoration team that knows the insurance game inside and out makes all the difference. We’ve been helping South Shore homeowners navigate these challenges for years, and we’re here when you need us most.
Frequently Asked Questions
Why don’t South Shore homeowners have flood coverage if they’re near the coast?
Many South Shore residents assume their homeowners insurance covers flood damage because they live near water, but standard policies exclude all flood damage regardless of location. Even homes in Hanover, Marshfield, or Scituate need separate flood insurance through the National Flood Insurance Program. About 20-25% of flood claims actually come from areas not considered high-risk, so coastal proximity doesn’t guarantee you need it, but it doesn’t provide automatic coverage either.
If my sump pump fails during a nor’easter, am I covered?
This depends on why your sump pump failed and what coverage you have. If it failed due to power outage or mechanical breakdown and you have sewer/water backup coverage (about $50/year), you’re likely covered. However, if the failure was due to lack of maintenance or if flooding overwhelmed the system, standard homeowners insurance typically won’t cover it. Given how many South Shore basements rely on sump pumps, this endorsement is usually worth the small annual cost.
What should I do immediately after discovering water damage to protect my insurance claim?
Document everything with photos before cleanup, stop the water source if safely possible, and contact both your insurance company and a restoration team quickly. The “sudden and accidental” rule means timing matters for your claim. RestoreNow can help coordinate emergency services with our licensed partners and ensure proper documentation that insurers require, taking that administrative burden off your shoulders during an already stressful time.
Are ice dams considered sudden and accidental for insurance purposes in Massachusetts?
Yes, ice dam damage is typically covered by homeowners insurance in Massachusetts because it’s considered a sudden weather event, even though ice dams are common here in winter. Your policy may cover both removing the ice dam portion causing the leak and repairing resulting water damage. However, if the ice dam formed due to poor attic insulation or ventilation that you knew about, the insurer might argue it was preventable.